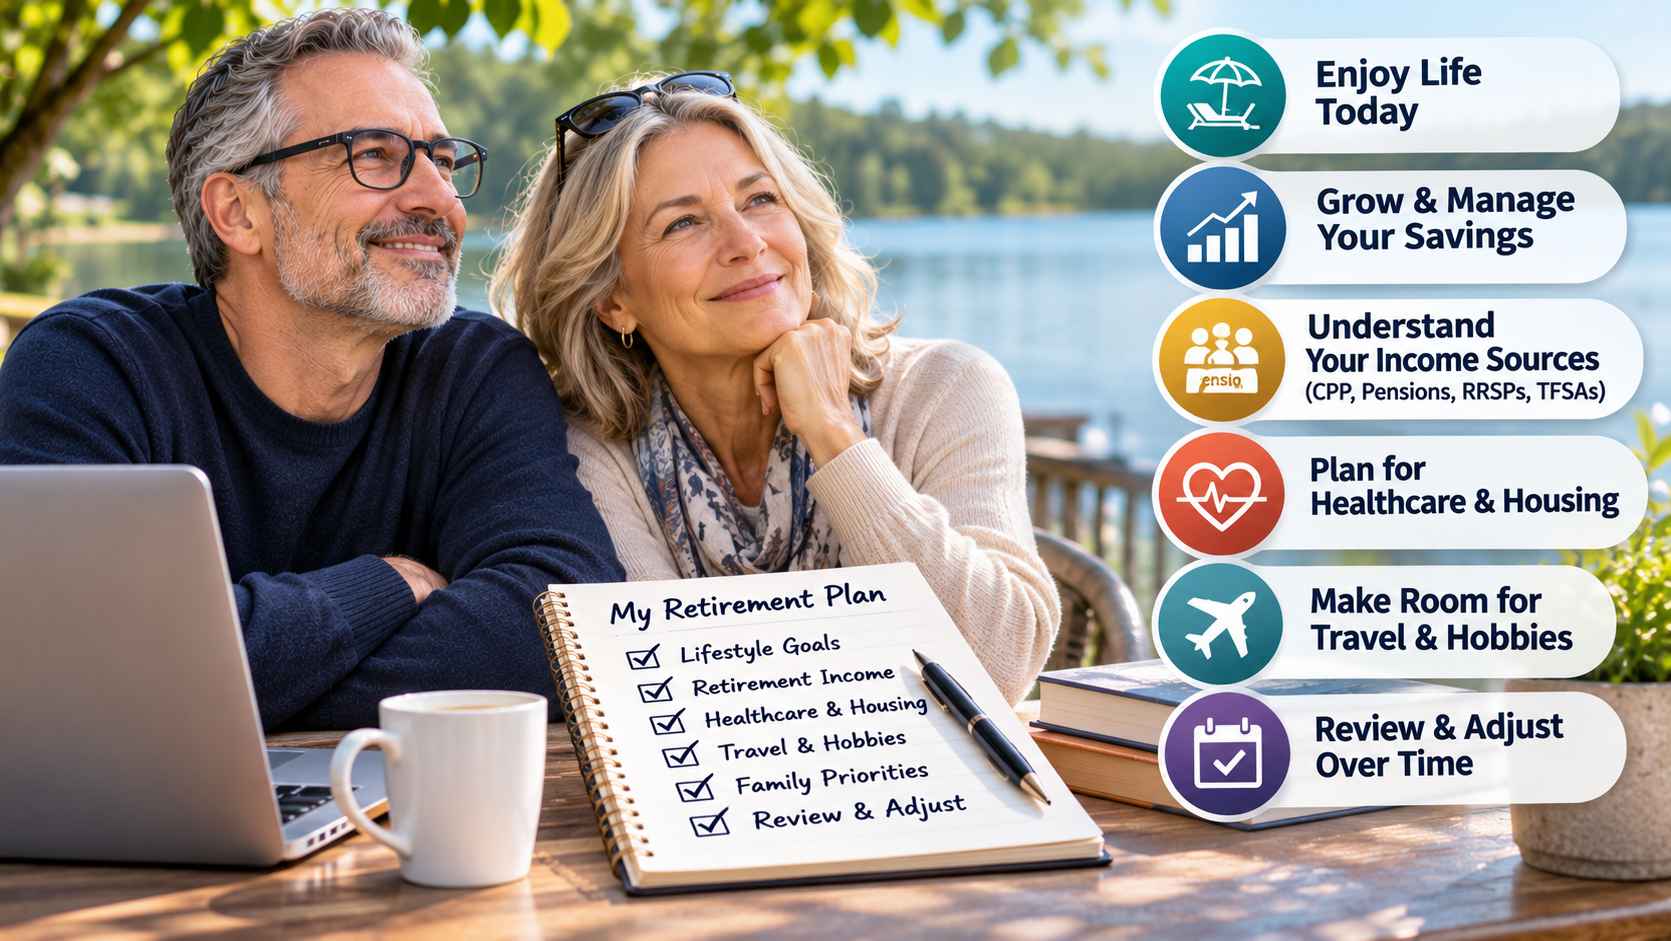
Planning for retirement often involves an important question: How much should you save for the future without giving up the experiences that make life enjoyable today?
For many Canadians, the answer is not straightforward. Between housing expenses, family responsibilities, travel plans, and everyday living costs, balancing present needs with long-term financial goals can feel challenging.
Some people focus heavily on retirement savings while postponing meaningful experiences. Others prioritize their current lifestyle without fully considering how their financial needs may change when they stop working.
A thoughtful retirement plan should recognize both priorities.
Rather than treating financial preparation and current enjoyment as competing goals, individuals can develop a practical approach that supports the lifestyle they value today while preparing for the years ahead.
Start by Defining What Retirement Means to You
Retirement looks different for everyone.
Some people imagine travelling frequently, spending more time with family, or pursuing hobbies. Others prefer a quieter lifestyle, volunteering, or gradually reducing their professional responsibilities.
Before estimating retirement expenses, it helps to understand what kind of life you want to create.
For example, someone planning to remain in their current home may have different financial priorities from a person hoping to relocate or spend part of the year travelling.
Consider Your Preferred Retirement Lifestyle
Ask yourself:
- Where would I like to live during retirement?
- Do I expect to travel regularly?
- Would I prefer to stop working completely or continue part-time?
- What hobbies and activities are important to me?
- Will I have ongoing financial responsibilities toward family members?
These questions provide direction for financial planning and help distinguish personal goals from general retirement expectations.
Estimate Future Living Expenses Realistically
Understanding retirement expenses is an important part of preparing financially.
Many people assume that spending will automatically decrease after leaving full-time employment.
However, expenses may change rather than simply disappear.
Commuting and work-related costs might decline, while travel, recreational activities, or other personal interests could become more significant.
Separate Essential and Flexible Expenses
Essential expenses may include housing, utilities, groceries, insurance, transportation, and healthcare-related costs.
Flexible spending might involve travel, entertainment, hobbies, and occasional major purchases.
Reviewing these categories helps individuals understand which expenses are necessary and which can be adjusted if circumstances change.
A realistic retirement budget should also consider irregular expenses, such as home repairs or replacing a vehicle.
Balance Retirement Savings With Today’s Priorities
Preparing for retirement does not necessarily require postponing every enjoyable experience.
A family might want to take vacations, support children’s education, or make improvements to their home while continuing to save for the future.
The challenge is determining how these priorities fit within available financial resources.
One approach is to establish separate goals for immediate expenses, medium-term plans, and retirement.
For example, money intended for an upcoming family vacation serves a different purpose from investments expected to support retirement decades later.
Professional retirement and financial planning can help individuals evaluate how current spending decisions interact with long-term objectives.
The goal is to make deliberate choices rather than treating every present-day expense as a threat to future financial security.
Understand the Difference Between Saving and Retirement Income
Accumulating retirement savings is only one part of financial preparation.
During working years, people generally focus on building assets through regular contributions and investments.
In retirement, the focus often shifts toward using those assets to support living expenses.
This creates a different set of considerations.
Building Retirement Assets
Savings may accumulate through employer pension plans, registered accounts, and other investments.
Generating Retirement Income
Once employment income decreases or ends, retirees need to consider how different financial resources will provide cash flow.
This may involve pension payments, government benefits, investment income, or withdrawals from accumulated savings.
The timing, tax treatment, and sustainability of withdrawals can influence the overall plan.
Understanding this transition helps people prepare for retirement as an ongoing financial responsibility rather than simply a savings target.
Review Pensions, RRSPs, TFSAs, and Other Resources
Canadian retirement planning often involves several potential income sources.
Registered Retirement Savings Plans (RRSPs) and Tax-Free Savings Accounts (TFSAs) have different contribution, withdrawal, and tax rules.
Employer pensions may provide additional retirement income, depending on the plan.
Government benefits can also form part of the overall picture.
The Government of Canada’s Canada Pension Plan retirement pension information explains eligibility, payment amounts, and considerations involving when benefits begin.
CPP provides a monthly taxable retirement benefit to eligible contributors, but individual payment amounts vary.
Other programs, including Old Age Security, may also be relevant depending on eligibility.
A complete retirement plan should consider these resources together rather than evaluating each independently.
Consider Inflation and Changing Living Costs
Inflation can affect the purchasing power of money over time.
Expenses that feel manageable during working years may change considerably over a lengthy retirement.
Housing, food, transportation, and personal services may all be affected by future price changes.
However, future inflation cannot be predicted with certainty.
Retirement planning should therefore consider different assumptions rather than relying on a single fixed estimate.
It is also useful to recognize that spending patterns may evolve.
Someone may travel frequently during the early years of retirement and later prefer activities closer to home.
A flexible financial plan should accommodate these possibilities without assuming that every stage of retirement will involve identical expenses.
Prepare for Healthcare, Housing, and Family Responsibilities
Retirement expenses extend beyond everyday purchases.
Healthcare needs, housing arrangements, and family responsibilities may influence future financial requirements.
Healthcare and Personal Needs
Although Canada’s public healthcare system covers many services, some expenses may involve prescription medications, dental care, vision services, or other needs not fully covered by an individual’s available plans.
Housing Considerations
Homeowners may need to budget for maintenance, repairs, property taxes, or accessibility improvements.
Renters should consider ongoing rental obligations and possible changes in housing needs.
Family Support
Some retirees may want to help children, grandchildren, or aging relatives.
Financial generosity should be considered alongside personal retirement security.
These priorities differ between households, making individualized planning particularly important.
Understand Investment Risk as Retirement Approaches
Investment risk remains relevant before and during retirement.
Market fluctuations can affect portfolio values, particularly when individuals need to begin withdrawing funds.
Someone approaching retirement may have different liquidity requirements and risk capacity from an investor with several decades before their planned retirement date.
Asset allocation, diversification, and expected withdrawals deserve careful consideration.
Professional professional investment management can provide a framework for reviewing portfolio objectives, investment risks, and changing income needs.
However, diversification and professional oversight cannot eliminate market risk or guarantee investment returns.
A suitable investment approach should reflect personal circumstances, not simply age or market predictions.
Review Your Retirement Plan as Life Changes
Retirement planning should not be treated as a one-time exercise.
Career changes, family developments, health concerns, and unexpected expenses may influence financial priorities.
For example, someone receiving an inheritance may need to reconsider retirement assumptions.
Another person choosing to reduce working hours earlier than planned may need to review expected income and spending.
Regular financial reviews can help identify whether existing arrangements remain consistent with personal goals.
These reviews may involve evaluating savings, debt, investments, retirement income expectations, and major upcoming expenses.
A financial plan should provide direction while allowing room for adjustments when circumstances change.
Build a Retirement Plan That Supports Both Stages of Life
Preparing for retirement is not simply about saving as much money as possible.
It involves understanding what matters personally, evaluating available financial resources, and deciding how to balance current experiences with future responsibilities.
A meaningful plan considers lifestyle goals, living expenses, pensions, investments, healthcare needs, and potential changes over time.
There is no universal retirement strategy that suits every Canadian household.
By setting realistic priorities, reviewing financial arrangements regularly, and seeking qualified guidance when appropriate, individuals can approach retirement preparation with greater clarity.
The purpose of planning is not to sacrifice the present for an uncertain future. It is to make thoughtful financial decisions that support a fulfilling life both before and during retirement.